How to Deal With the At-Fault Driver’s Insurance Company
You’re sore, your car is in a shop or a tow yard, and your phone rings. It’s a friendly voice from the other driver’s insurance company. They just want to “hear your side” and “get this wrapped up quickly.”
It sounds harmless. It isn’t always.
Dealing with the at-fault driver’s insurance company is one of the most important parts of any car accident claim, and one of the easiest places to make an expensive mistake. This guide walks you through what to do, what to say, and what to avoid so you’re not the person who accepts $2,000 on a claim that was worth much more.
Quick note: I’m a blogger, not a lawyer, and this isn’t legal advice. Laws differ by state, so use this as a starting point and talk to a licensed attorney about your specific case.
First, Understand Who You’re Dealing With
The other driver’s insurer is not your insurer. They don’t owe you a duty to protect your interests. Their job is to protect their policyholder and their own bottom line.
That doesn’t make the adjuster a villain. Most are polite and professional. But every claim they close for less is money the company keeps. Keep that in mind on every call, and you’ll already be ahead of most people.
Do You Have to Talk to Them?
In most situations, no. As the injured party, you generally have no legal obligation to speak with the at-fault driver’s insurance company or give them a recorded statement.
Here’s a distinction that trips people up:
- Your own insurance company: Your policy usually requires you to report the accident promptly and cooperate with their investigation. Do this quickly.
- The other driver’s insurance company: You’re a claimant, not their customer. You can decline a recorded statement, and you can tell them to communicate in writing or through your attorney.
Adjusters sometimes make it sound like a recorded statement is a formality. It’s not. It’s a piece of evidence that can be played back later to argue you were partly at fault or that your injuries weren’t serious.
Before You Say a Word to Any Insurer
Get your ducks in a row first. A few things to handle before the serious conversations begin:
1. Get medical care, even if you feel okay.
Adrenaline hides pain. Whiplash, concussions, and soft tissue injuries can take days to show up. A medical record made soon after the crash also protects you from the “if you were really hurt, you’d have seen a doctor” argument.
2. Collect and save your evidence.
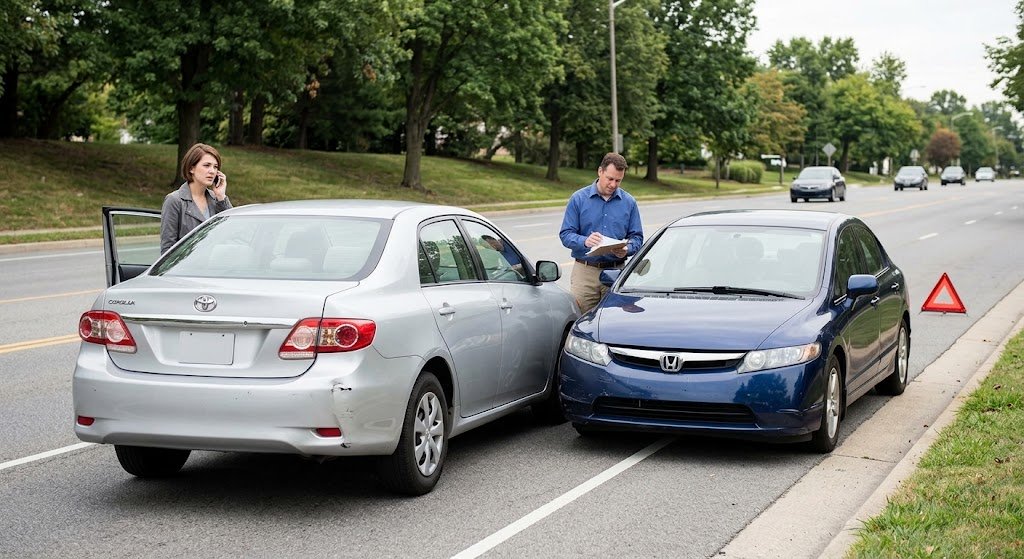
Photos of both vehicles, the road, skid marks, and traffic signs. The police report number. Names and numbers of witnesses. Screenshots of any texts or messages about the accident. Dashcam footage if you have it.
3. Start a claim journal.
Write down the date, time, name, and summary of every call with any insurance company. Save every email. Keep receipts for everything, including prescriptions, rental cars, and parking. It feels tedious, but this paper trail is what backs up your numbers later.
4. Notify your own insurer.
Even when the other driver clearly caused the crash, tell your own company. It keeps you in compliance with your policy, and it opens up coverage options that can help, which we’ll cover below.
What to Say When the Other Insurer Calls
Your first call will probably come within a day or two. Keep it short, calm, and boring. Boring is good.
It’s fine to share:
- Your name and contact information
- The date and location of the accident
- The make and model of your vehicle
Politely avoid:
- Recorded statements
- Describing exactly how the crash happened
- Guessing about speeds, distances, or timing
- Saying “I’m fine” or “I’m okay”
- Discussing your injuries or medical history
- Signing anything
A simple script that works:
“Thanks for calling. I’m not ready to give a statement right now. Please send me your claim number and adjuster contact info in writing, and I’ll follow up.”
That’s it. You don’t need to argue, explain, or apologize. If they push, repeat yourself. If you’ve hired an attorney, the line is even simpler: “Please direct all communication to my lawyer.”
The Common Tactics to Watch For
Knowing how these conversations tend to go makes them a lot less stressful.
The quick, friendly settlement offer. A fast check can feel like relief, especially if you’re missing work. But early offers often come before the full extent of your injuries is known. Once you accept and sign a release, you generally can’t ask for more later, even if your treatment turns out to cost far more than expected.
The recorded statement. Casual questions like “How are you feeling today?” get answered with “Fine, thanks,” and that’s now on tape as proof you weren’t injured.
The blanket medical authorization. Some insurers ask you to sign a form giving them access to your entire medical history. That lets them dig for old conditions to blame for your pain. It’s reasonable to share records related to the accident. It’s risky to hand over everything without guidance.
Shifting the blame. You might hear “Well, you were also going a bit fast, weren’t you?” Many states reduce your compensation by your percentage of fault, and a few bar recovery entirely if you’re partly to blame. Don’t accept blame you haven’t earned.
Delay. Slow replies, missing paperwork, and “we’re still reviewing” can wear you down until a low offer starts to look appealing. Stay consistent, follow up in writing, and keep your journal.
Social media snooping. Adjusters do look at public profiles. A photo of you at a family barbecue can be twisted into “she’s clearly not that hurt.” Set your accounts to private and don’t post about the accident or your recovery.
Property Damage vs. Injury Claims
These are two separate parts of the same accident, and they often move at different speeds.
Property damage covers your vehicle repairs or replacement. If your car is totaled, the insurer pays its market value, not what you owe on it. If the first number feels low, you can push back with comparable listings for the same year, mileage, and condition. Also ask about diminished value, the drop in resale value a car suffers after an accident even when it’s repaired well. Many people never ask, and some states allow it.
Bodily injury covers medical bills, lost income, pain and suffering, and future treatment. This is the bigger, more complicated claim, and the one where mistakes cost the most. Don’t settle it until you understand the full extent of your recovery. That usually means waiting until you’ve reached maximum medical improvement, or until your doctor can give you a clear picture of what’s ahead.
How to Push Back on a Lowball Offer
If you get an offer that doesn’t cover your costs, you don’t have to accept it or take it personally. Here’s how to respond:
- Don’t accept or reject on the spot. Say you’d like the offer in writing so you can review it.
- Add up your real losses. Medical bills, future care, lost wages, rental costs, and out-of-pocket expenses.
- Send a written counteroffer. Include your documentation and a clear number, with a short explanation of how you got there.
- Keep everything in writing. It creates a record and keeps emotions out of it.
- Know when to escalate. If the insurer won’t move, that’s usually the point to consult a lawyer.
Your Own Insurance Can Help, Too
Sometimes going through your own policy is faster and less painful than waiting on the other driver’s company. Depending on your state and coverage, options may include:
- Collision coverage: pays to repair your car regardless of who was at fault. Your insurer may then try to recover the money from the other company (called subrogation).
- Medical payments (MedPay) or personal injury protection (PIP): helps with medical bills quickly, without waiting for a fault decision.
- Rental reimbursement: covers a rental while your car is repaired.
- Uninsured/underinsured motorist coverage: protects you when the at-fault driver has no insurance or too little of it.
Check your policy declarations page or call your agent to see what you actually have. Many people are surprised by what they’re already paying for.
What If the At-Fault Driver Has No Insurance?
It happens more often than you’d think. Your main options are usually:
- Filing under your own uninsured motorist (UM) coverage, if you have it
- Using collision or MedPay coverage for immediate costs
- Pursuing the driver personally, though collecting from someone with no insurance and limited assets can be difficult
If the other driver has insurance but the limits are too low to cover your damages, underinsured motorist (UIM) coverage may fill the gap. Rules and deductibles vary by state, so read your policy carefully.
When It’s Worth Hiring a Personal Injury Lawyer
Not every accident needs an attorney. A minor fender bender with no injuries and a cooperative insurer can often be handled on your own.
It’s smart to at least talk to a car accident lawyer if:
- You had significant injuries, surgery, or ongoing treatment
- You missed a lot of work or can’t return to your job
- Fault is disputed or the insurer is blaming you
- The insurer is delaying, ignoring you, or denying the claim
- The settlement offer seems far below your actual costs
- Multiple parties or a commercial vehicle were involved
- You’re unsure what your claim is really worth
Most personal injury attorneys offer free consultations and work on a contingency fee, meaning they’re paid a percentage only if you recover money. That makes it low-risk to get an opinion. Ask about fees, expected timelines, and how they’d handle your case before you sign anything.
Also keep in mind that every state has a statute of limitations, a deadline to file a lawsuit. Waiting too long can permanently end your right to compensation, so don’t let a slow claim drag on without knowing your deadline.
Common Mistakes That Cost People Money
- Giving a recorded statement without thinking it through
- Accepting the first offer
- Settling before treatment is finished
- Skipping doctor visits or gaps in treatment
- Posting about the accident or your activities online
- Signing broad medical releases or settlement paperwork without reading it
- Missing deadlines
- Not keeping records
Quick Checklist
- ✅ Get medical care and follow your treatment plan
- ✅ Report the accident to your own insurer
- ✅ Save photos, reports, receipts, and messages
- ✅ Decline recorded statements from the other insurer
- ✅ Keep all communication in writing when possible
- ✅ Never accept a first offer without reviewing it
- ✅ Stay off social media about the accident
- ✅ Talk to an attorney if injuries are serious or the insurer is difficult
Final Thoughts
Dealing with the at-fault driver’s insurance company doesn’t have to be scary, but it does require you to be careful. Stay calm, keep it short, get everything in writing, and don’t rush into a settlement you can’t take back. If your injuries are serious or the insurer isn’t playing fair, getting professional advice early can protect both your health and your finances.
Disclaimer: This article is for general information only and isn’t legal or insurance advice. Laws and policies vary by state and situation. Consult a licensed attorney or your insurance agent about your specific case.
FAQ section (optional, good for featured snippets and schema):
Should I talk to the other driver’s insurance company?
You’re usually not required to. It’s safest to give only basic facts, decline a recorded statement, and direct them to your insurer or attorney.
Should I accept the first settlement offer?
Generally no. First offers are often low and made before your full injuries and costs are known.
Can the at-fault driver’s insurance use my words against me?
Yes. Statements you make, especially recorded ones, can be used to dispute fault or downplay injuries.
What if the other driver’s insurance won’t return my calls?
Follow up in writing, keep records, and consider filing through your own insurer or consulting an attorney.
How long do I have to file a claim?
It depends on your state’s statute of limitations and your policy’s reporting rules. Don’t wait.
About the Author